How many stocks make a diversified portfolio?
A stock count alone does not tell you how diversified a portfolio is. Weights, shared exposures and behaviour during bad periods matter too.
Ask someone who has rented out flats for twenty years which ones retain their value over time. They will not list individual addresses. They will talk about characteristics: location, construction, light and clean paperwork. They can be wrong about one flat, but those characteristics matter across a hundred.
Equity markets have a similar way of thinking, known as factor investing. A factor is a measurable characteristic shared by many companies that research has associated with differences in long-run returns. Factor investing applies the same rules, written in advance, across a broad set of stocks instead of guessing the fate of one company. Every claim concerns a group average and says little about any single stock. There are no guarantees even for the group. Historical patterns can weaken or reverse for long periods.
Researchers have described dozens of factors. Three of the best studied are also among the easiest to understand.
The value factor. The rule looks for stocks with a lower price relative to book value, earnings or other company fundamentals. In 1992, Eugene Fama and Kenneth French showed that book-to-market ratios strongly described differences in average returns among US stocks. Be careful with the word undervalued. The rule measures a relative price and does not prove that a business is worth more. Some companies are cheap for good reason.
The momentum factor. The rule ranks stocks by their returns over the previous few months to one year. In 1993, Narasimhan Jegadeesh and Sheridan Titman documented that past winners in their samples continued, on average, to outperform past losers for a time. The rule is a consistent ranking of the full stock universe, with rules set in advance for when a position changes.
The quality factor. The rule favours profitable, financially sound and stable companies. Profitability is its best-studied component. Robert Novy-Marx showed in 2013 that gross profit relative to assets separated groups of companies with different average returns. Broader definitions, such as Quality Minus Junk by Asness, Frazzini and Pedersen, also include growth, safety and payouts to owners. Quality is therefore a family of related measures.
| Factor | What the rule measures | What the group rule assumes |
|---|---|---|
| value | price relative to book value, earnings or other fundamentals | that unpopular, cheaper companies as a group may earn higher average returns than expensive ones |
| momentum | a stock's return over the previous few months to one year | that recent trends may continue for a time on average |
| quality | profitability, debt and business stability | that the market sometimes prices stable, well-run companies too low |
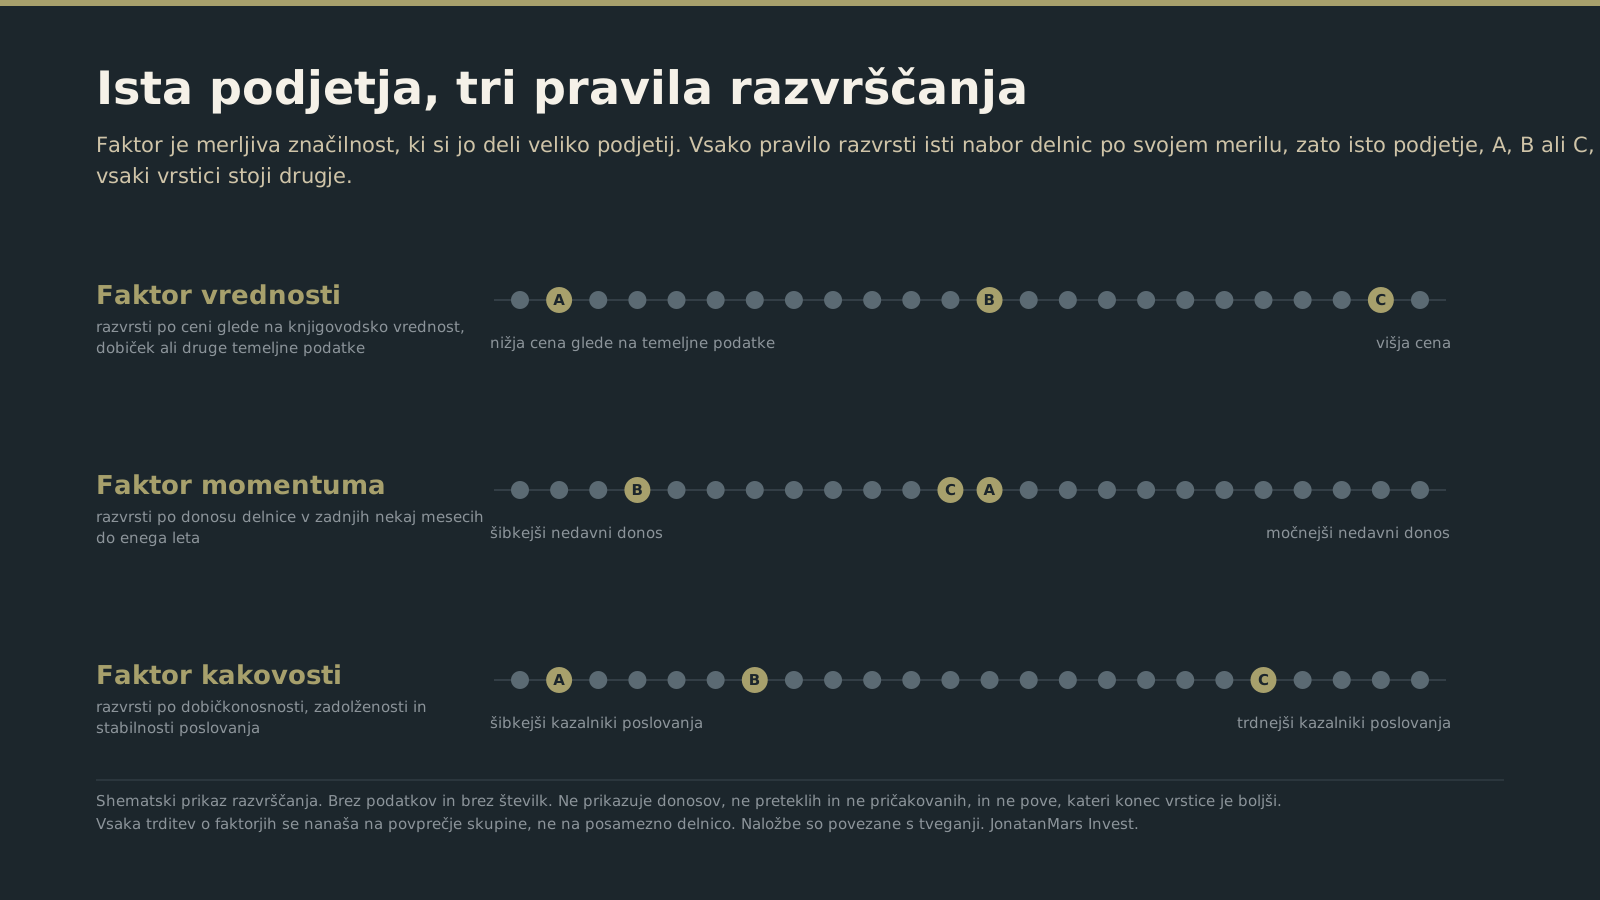
These patterns do not rest on one US dataset. In 2012, Fama and French found value in North America, Europe, Japan and Asia Pacific, and momentum in every one of those regions except Japan. Asness, Moskowitz and Pedersen found related value and momentum patterns in eight markets and asset classes: individual stocks in the US, the UK, continental Europe and Japan, plus country equity index futures, government bonds, currencies and commodity futures. The authors of Quality Minus Junk tested their broader quality definition in the US and 24 countries. Broad evidence does not mean that a factor works everywhere and at all times. Japan, where momentum did not show up in this study, is a serious exception.
If everyone knows the pattern, why does the market not remove it? Research offers three overlapping explanations, none of them proven conclusively. In our view, investor behaviour and institutional constraints explain most of it, while part may remain fair compensation for risk.
First, behaviour. People tend to extend recent growth too far into the future. We assign too much value to attractive stories and too little to dull or disappointing companies. Lakonishok, Shleifer and Vishny showed how this kind of extrapolation can create the price differences used by the value factor. Momentum has a related explanation. Hong and Stein showed how information can spread slowly among investors, causing prices to adjust to news gradually.
Second, institutional constraints. Professional managers have benchmarks, mandates, borrowing limits and clients who withdraw capital after losses. Shleifer and Vishny showed that capital capable of correcting a pricing error may leave precisely when that error is largest. A mispricing can therefore persist even when many investors see it.
Third, risk. Part of the historical difference may compensate investors for bearing risks that others avoid. This is clearest among the smallest companies. Their shares are less liquid, expensive to trade and unable to absorb much capital. Smaller companies also tend to have fewer analysts following them than large ones. Here a warning is needed. Hou, Xue and Zhang retested a large number of published return patterns. Many disappeared when the smallest stocks no longer received excessive weight. Part of the measured difference was therefore a result of the measurement method.
For quality, the risk explanation is weakest because profitable companies tend to be less fragile. Its behavioural explanation is also the least settled. The evidence that profitability predicts returns is stronger than the evidence for why the market might overlook it.
Cliff Asness of AQR offers a useful middle ground. A factor can persist because some investors bear risk while others repeat mistakes. As more people learn the pattern, any premium may shrink without disappearing entirely. This is a manager's reasoned opinion and does not carry the weight of proof.
A factor portfolio deliberately differs from the market, so it will look wrong for long periods. Linnainmaa and Kalesnik of Research Affiliates count this among the most overlooked risks of factor investing. Each of these three factors has spent years lagging the broad market. Momentum also suffers rare but severe episodes. Daniel and Moskowitz documented momentum crashes during sharp recoveries after market panics. An investor who abandons the rule in the middle of such a period sells when staying with it is hardest. Cullen Roche, author of the Pragmatic Capitalism blog, asks how many investors can really endure that long. That is why Smart Beta does not rely on one factor. The factors are only weakly related to each other, so one factor's bad years often do not coincide with another's. There is no guarantee that they will not.
Implementation is not free either. Momentum requires substantial trading, so costs, bid-ask spreads and fees can consume part of the pattern measured on paper. Novy-Marx and Velikov showed how much depends on turnover. Wesley Gray of Alpha Architect points to another trap. A fund or portfolio carrying a factor label can differ greatly from the research portfolio in a paper, and two solutions with the same label can hold very different investments. McLean and Pontiff also showed that published patterns tend to weaken outside their original data periods. Moderate expectations are therefore part of an honest explanation.
Factor investing does not promise that the future will repeat the past. It offers something more modest and, in our view, more useful: rules written in advance, which you understand before investing and which do not require guesses about individual companies.
Value, momentum and quality are therefore three rules written in advance that rank stocks by price, by recent return, and by profitability and financial strength. At JonatanMars Invest, these three factors are part of the Smart Beta strategy, together with company size, low volatility and equal weighting, and we rebalance the portfolio once a quarter. Luka Gubo, director and lead investment manager, is accountable for the process. There are no guarantees: even six factors together can lag the broad market for years, so we explain the process together with the periods when it will look as if it is not working.
If you would like to talk it through, book a free introductory consultation.
Does factor investing guarantee higher returns?
No. Factors describe historical differences in the average returns of groups of stocks. Each has endured long periods of underperformance, and nobody can guarantee that historical patterns will repeat.
Is momentum the same as buying fashionable stocks?
No. Momentum is a predefined rule that ranks a full stock universe by returns over recent months and changes positions through a clear process. Chasing fashionable stocks means making case-by-case decisions, usually without an exit rule.
Is every value stock undervalued?
No. The value factor measures relative price against fundamentals. Some companies are cheap because their business is deteriorating. The rule is therefore applied across broad, diversified groups of stocks.
Why do factors not disappear once everybody knows about them?
Part of the difference may compensate for risks many investors do not want to bear. Part may arise from repeated behavioural errors and institutional constraints that are hard to remove. Any premium can still shrink as the approach becomes more widely used.
How long can a factor lag the market?
For several years in a row. All three factors have experienced extended periods behind the broad market. Momentum also has rare but severe crashes during sharp rebounds after market panics. Investors unable to hold factors through such periods are unlikely to benefit from them.
Are factors suitable for me?
A general article cannot answer that. Suitability depends on your assets, goals and attitude to risk. This is a general explanation, not personal investment advice.
This is a marketing communication and general educational material, not personal investment advice.
Investing involves risk. The value of investments may fall as well as rise, and you may receive less than you invested. Past and any simulated or tested returns are not a reliable indicator of future returns. Tax treatment depends on personal circumstances and applicable law, both of which may change.
Luka Gubo is director and lead investment manager at JonatanMars Invest. He has been trading and investing since 2006.
More insights
A stock count alone does not tell you how diversified a portfolio is. Weights, shared exposures and behaviour during bad periods matter too.
How to distinguish an attractive backtest from a result that is reproducible, robust and investable after costs.
Volatility is useful, but it does not capture permanent loss, liquidity, inflation or rare events. A smooth chart is not proof of safety.
Stay in touch